How to Distribute Performance Bonuses? Calculation Methods, Ratios, and Distribution Rules | Recommended Performance Management System
This article explains the legal recognition of performance bonuses (wages vs. discretionary benefits), common calculation methods (fixed multiplier method, KPI achievement rate linking method, profit-sharing method), principles for ratio design, relationships with severance pay and retirement benefits, income tax and Second Generation Health Insurance supplementary premium calculations, and how to manage the entire distribution process using the 管理王 system.
Performance bonuses are additional compensation paid by companies based on employees' achievement of goals, with the amount, frequency, and conditions determined by the employer, and no statutory formula exists. Many employers are unclear about whether performance bonuses are considered 'wages,' how to design the distribution ratio, and whether taxes should be deducted after payment—if these issues are not clarified, it can lead to overpayment of taxes or affect the calculation of severance pay, and even result in labor disputes. This article organizes the legal recognition standards, calculation methods, ratio design principles, tax regulations regarding performance bonuses based on labor laws and Ministry of Finance tax regulations to assist Taiwan's SMEs in establishing a legal and transparent performance bonus system.
Are Performance Bonuses Considered Wages? Legal Recognition Standards
This is the most important question regarding performance bonuses, yet it is often overlooked. The answer is not simply 'yes' or 'no,' but rather 'it depends on the circumstances.'
According to Article 2, Paragraph 3 of the Labor Standards Act, the definition of wages is:
> "Compensation received by workers for their labor, including wages, salaries, and any regular payments in cash or in kind made as bonuses or allowances based on hourly, daily, monthly, or piece rates."
Note the phrase 'any regular payments in any form'—this means that the name does not matter, what matters is whether it meets the essence of 'wages.'
The implementation rules of the Labor Standards Act, Article 10 lists exclusions from 'non-wages,' which includes 'year-end bonuses, competition bonuses, research and invention bonuses, special merit bonuses, long-service bonuses, and other non-regular bonuses.' 'Performance bonuses' do not appear on this exclusion list.
What Does the Ministry of Labor Say?
Letter No. 035198 from the Council of Labor Affairs of the Executive Yuan (87) explicitly states:
> "If performance bonuses are paid based on workers achieving predetermined goals, they have the nature of compensation for work and should be categorized as wages according to Article 2, Paragraph 3 of the Labor Standards Act and Article 10 of its implementation rules. They should be included in the calculation of average wages for retirement pay."
However, The Supreme Court's Verdict No. 106 (89) has another opinion: If performance bonuses are linked to company profits and supervisor approval, they ‘are not regular payments for labor provided by workers but are rewards and discretionary benefits provided by employers to encourage employee morale and do not constitute wages.’
In Summary
Whether performance bonuses are considered 'wages' depends on two criteria: the compensation for labor (achievable upon meeting work goals) and regularity (distributed periodically and consistently); if both conditions are met, they should be included in severance pay and retirement calculations.
Table: Two Criteria for Determining Performance Bonuses as Wages
| Criteria | Considered Wages | Not Considered Wages |
|---|---|---|
| --- | --- | --- |
| Compensation for Labor | Achievable upon meeting work goals, clear conditions | Dependent on company profits and supervisor approval |
| Regular Payment | Distributed regularly every month or quarter | Occasional, irregular, one-time distributions |
Therefore, when companies design performance bonus systems, they should explicitly stipulate the distribution conditions, calculation formulas, and distribution cycles in labor contracts or work regulations to accurately manage legal risks.
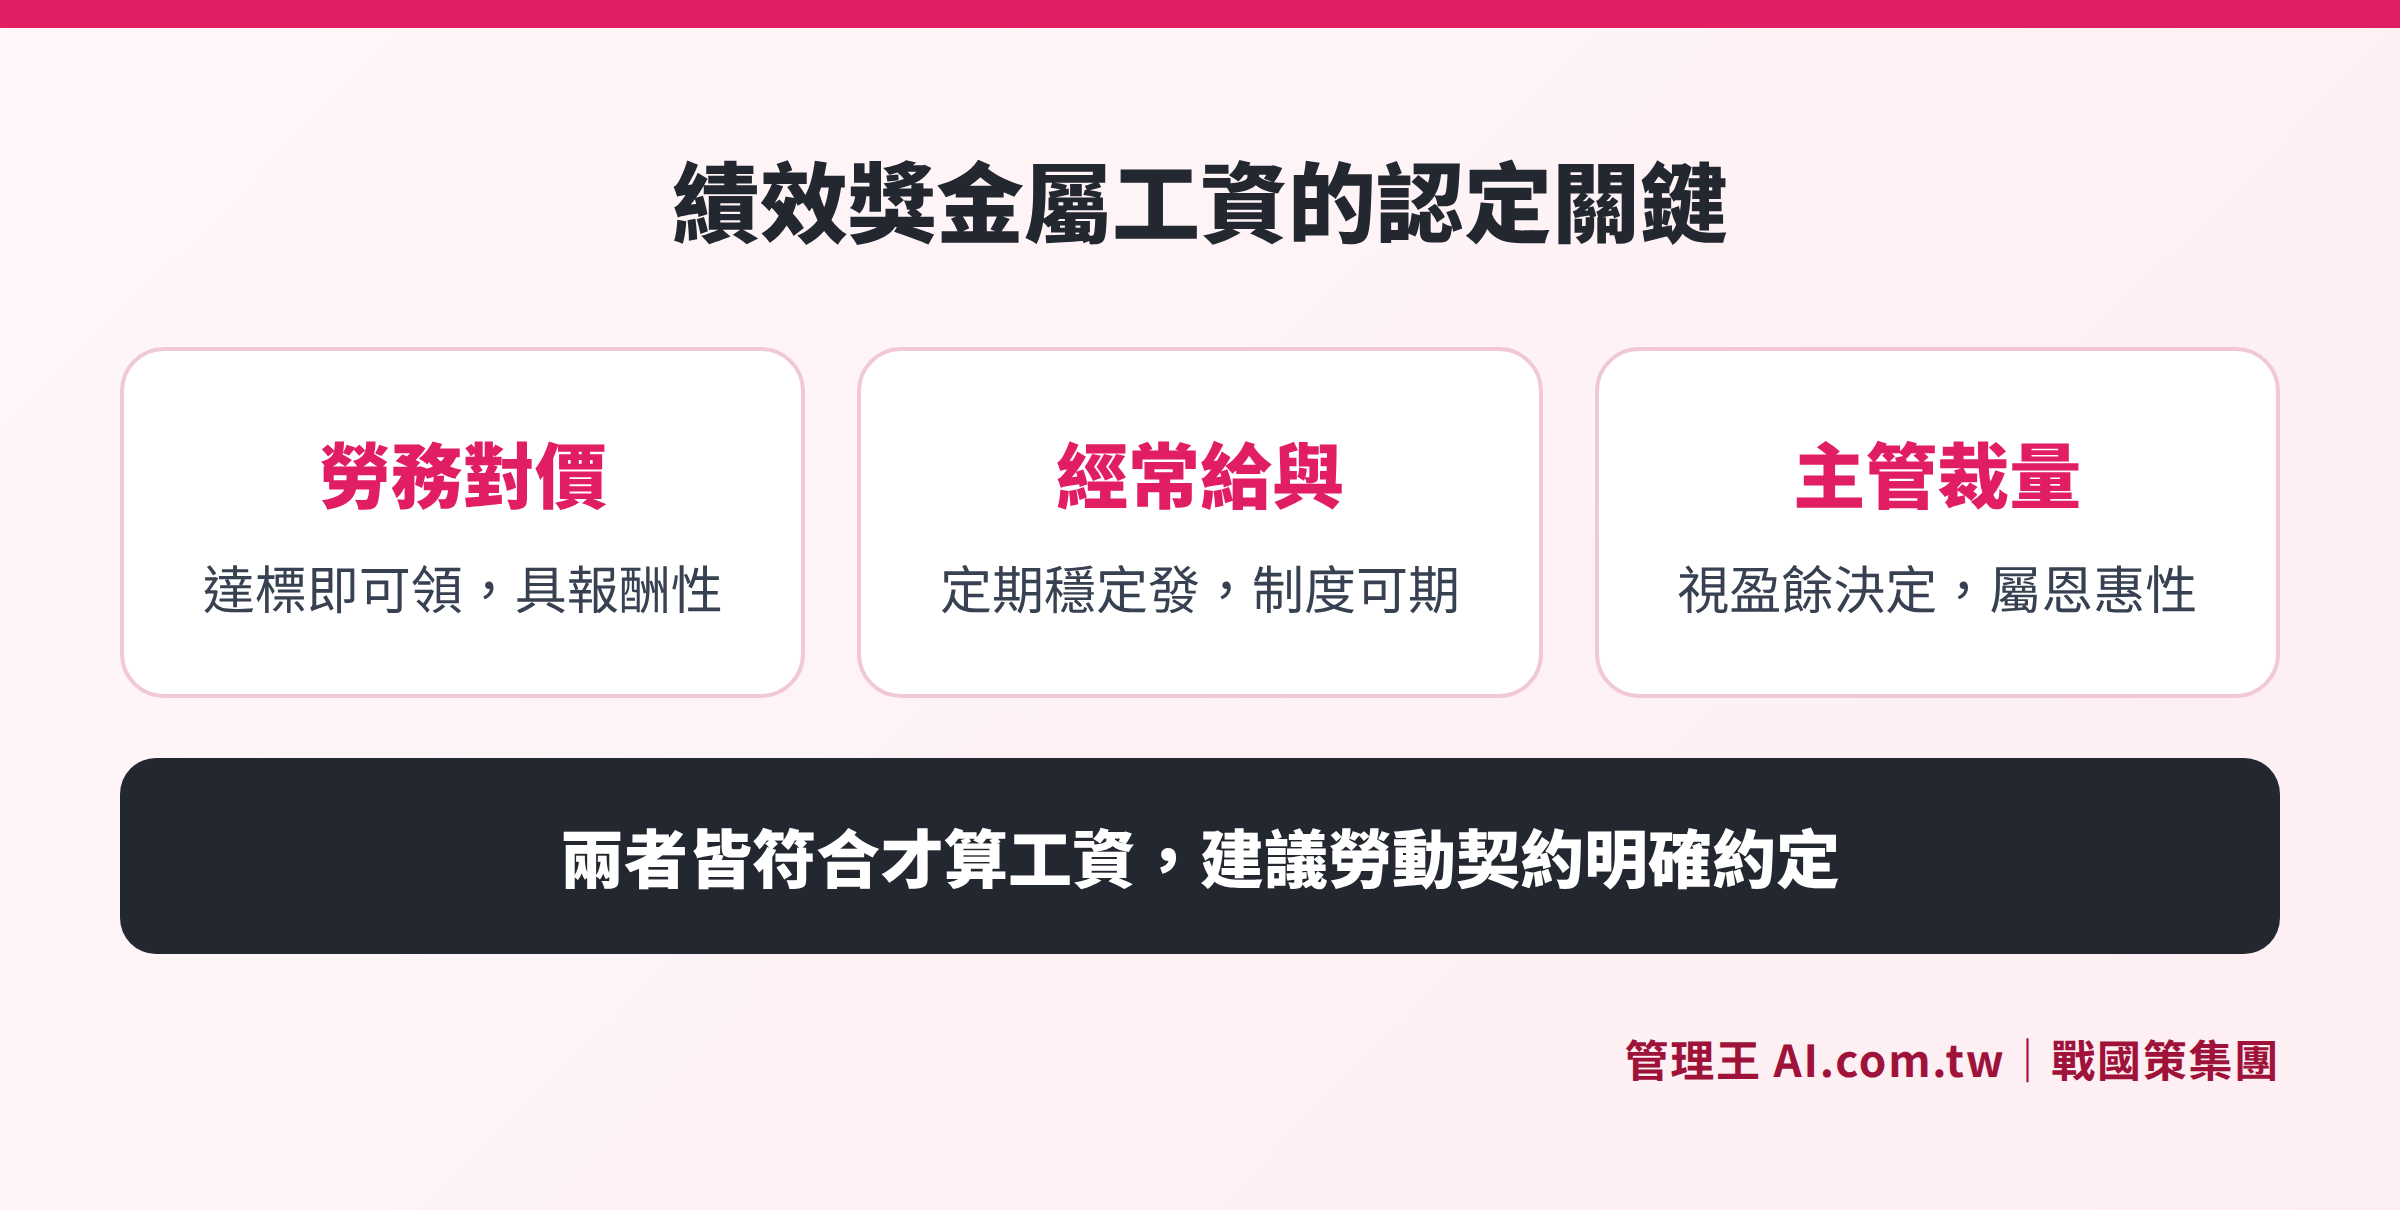
Comparison of Compensation for Labor, Regular Distribution, and Supervisor Discretion
What Are the Calculation Methods for Performance Bonuses?
There are three common calculation structures on the market; companies can choose the most suitable method based on the nature of their industry and job categories:
1. Fixed Multiplier Method (based on base salary)
This is the most straightforward and easy for employees to understand. The formula is:
Performance Bonus = Monthly Salary × Performance Multiplier
The multiplier usually varies depending on ratings (such as S, A, B, C); employees with higher ratings receive higher multipliers, while those who fail to meet the threshold may receive no bonus. The multiplier's level is determined by the company based on budgets and industry practices, with no statutory standard.
2. KPI Achievement Rate Linking Method
This method calculates the bonus ratio based on the weighted score achieved against the KPI for the period. The formula is:
Performance Bonus = Bonus Baseline × KPI Weighted Achievement Rate
For example: If the bonus baseline is defined as a certain percentage of the monthly salary, and the KPI achievement rate exceeds 100%, the employee may receive more than the baseline; if they fail to meet the goals, the amount decreases proportionally. This method best reflects individual performance, especially suitable for positions in sales, marketing, and other areas with clear quantitative indicators.
3. Profit-Sharing Method
This involves distributing a certain percentage of the company's after-tax profits for a period or departmental profits to employees based on their contributions. It is common among department heads or senior executives and is highly linked to the company's overall benefits, but it is more affected by market conditions, resulting in less income predictability for employees.
4. Mixed Method
Many companies use both individual KPI achievement rates and overall departmental/company performance metrics, calculating each separately before combining them weighted to balance individual contributions and team collaboration.
Table: Comparison of Three Performance Bonus Calculation Methods
| Calculation Method | Applicable Targets | Advantages | Cautions |
|---|---|---|---|
| --- | --- | --- | --- |
| Fixed Multiplier Method | General staff, factory workers | Simple rules, easy to understand | Multiplier design must fit within the company budget |
| KPI Achievement Rate Linking Method | Sales, PM, Marketing | Directly linked to targets, fair, objective | Quality of KPI settings affects results |
| Profit-Sharing Method | Senior executives, sales managers | Aligned with company interests | Greatly affected by market conditions, unstable |
| Mixed Method | Mid-level managers, cross-functional teams | Balancing individual and team performance | Formulas are more complex and need thorough explanation |
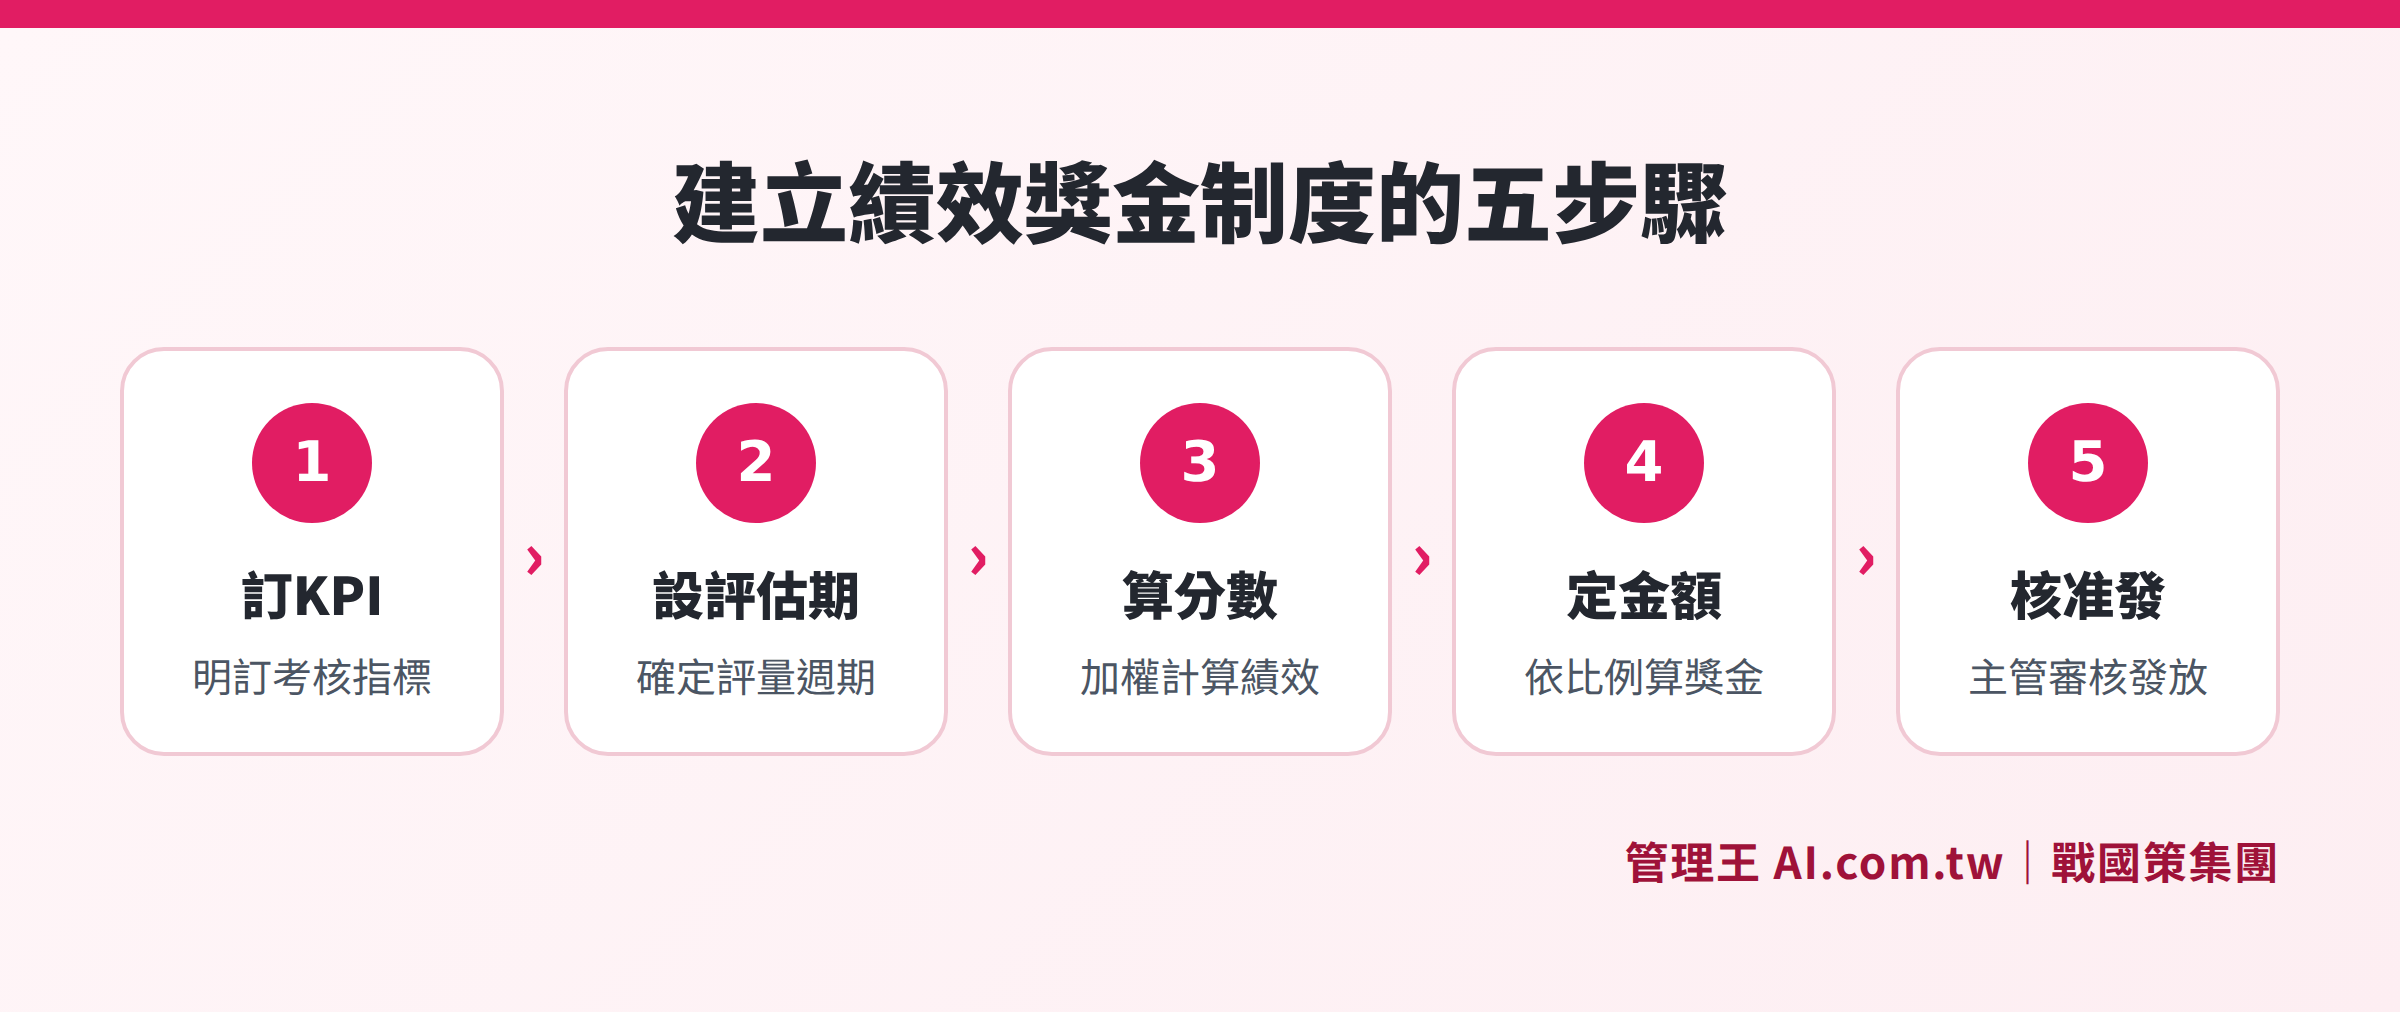
The complete process from setting KPIs to approving distributions, ensuring every step has systematic records
How to Set Performance Bonus Ratios?
The design of the 'ratio' does not have a statutory standard; companies can decide based on their budgets and management goals. Still, they must pay attention to the following four aspects:
1. Clearly Write in Labor Contracts or Work Rules
If the conditions for bonuses are clear and periodically distributed, they may be recognized as wages. If a company wants to retain flexibility (for example, not issuing bonuses in loss years), it should clearly state in the labor contract that 'bonuses are determined by company profits and personal performance, not part of guaranteed salary' and have employees sign to confirm. If the company wishes to incentivize employees directly with performance bonuses, clear achievement thresholds and multipliers can be designed so that employees understand the concrete rewards for their efforts.
2. Link with KPI Systems
The ratios should correspond with assessment periods and target achievement thresholds. It is recommended to set achievement thresholds (e.g., no bonuses if the achievement rate does not meet a certain level) to ensure bonuses genuinely reflect performance differences rather than everyone receiving a reward.
3. Budget Control
Include the total amount of performance bonuses for the entire company in the annual human resources cost budget to avoid the situation of 'overspending after distribution.' A common practice is to first determine the total bonus pool, then allocate it to various departments based on their rating proportions, which department heads further distribute to individuals.
4. Cross-Department Calibration
Avoid situations where one department is too lenient in scoring while another is strict, resulting in employees with equivalent efforts receiving vastly differing bonuses, thereby affecting morale. It is recommended to hold calibration meetings at each assessment period to unify scoring criteria, ensuring comparability across teams' scores. 管理王's Performance Management System has an in-built calibration meeting function to help HR align scoring across departments.
What is the Difference Between Year-End Bonuses, Performance Bonuses, and Attendance Bonuses?
Many people confuse 'year-end' and 'performance,' but their legal nature is entirely different, and they impact salary costs differently.
Year-End Bonus:
Article 29 of the Labor Standards Act states: "At the end of the business year, if there are profits, after paying taxes, offsetting losses, and allocating dividends and reserve funds, a business unit should grant bonuses or distribute dividends to employees who worked all year without fault."
Conditions: There must be profits + employees must have no faults throughout the year for there to be a statutory obligation. Article 10 of the Implementation Rules of the Labor Standards Act also specifies 'year-end bonuses' as non-wages, generally not included in average wage calculations (unless the labor contract guarantees a certain number of months).
Performance Bonus:
This does not appear on the exclusion list and must be recognized on a case-by-case basis based on the 'compensation for services' and 'regularity'; the legal definition is more controversial as explained earlier.
Attendance Bonus:
The Council of Labor Affairs of the Executive Yuan specifies (Letter No. 040204) that the attendance bonus is given based on attendance conditions, 'which has the nature of compensation for services and should be classified as wages,' and must be included in calculations for overtime pay, severance, and retirement without controversy in recognition.
Table: Comparison of Three Common Bonus Types
| Comparison Item | Year-End Bonus | Performance Bonus | Attendance Bonus |
|---|---|---|---|
| --- | --- | --- | --- |
| Legal Nature | Discretionary benefit or wage (depending on agreement) | Subject to recognition based on payment conditions | Clearly classified as wages |
| Exclusion List in Implementation Rules | Clearly listed as non-wages | Not listed, not applicable to exclusions | Not listed |
| Included in Average Wages | Generally no (unless guaranteed months) | Dependent on recognition results | Yes |
| Statutory Obligation | Must be paid if there are profits + no employee faults | Based on labor contract provisions | Should be paid based on attendance |
Do Performance Bonuses Affect Severance Pay and Retirement Benefits?
If performance bonuses are classified as wages, they must be included in the calculation of 'average wages,' which in turn affects the amounts of severance pay and retirement benefits.
According to Article 2, Paragraph 4 of the Labor Standards Act, the average wage is defined as: "The total amount of wages received in the six months prior to the occurrence of the calculation reason divided by the total number of days in that period."
If there are performance bonuses recognized as wages during those six months, it will raise the average wage and influence the following items:
New Severance Pay (Labor Retirement Pension Act, Article 12)
Half a month's average wage paid for each full year worked; if less than one year, pro-rated; with a maximum payment of six months' average wage. If performance bonuses are included, the severance pay amount for employees in the same year will be higher than the calculation results based on just monthly salaries.
Old Retirement Benefits (Labor Standards Act, Article 55)
Retirement benefits calculated based on years of service and average wages; if the average wage increases due to the inclusion of performance bonuses, the retirement benefit amount will also increase accordingly, requiring companies to incorporate this into their human resource cost planning.
Basis for Overtime Pay Calculation
If performance bonuses are wages, the 'normal wage' should include the portion of performance bonuses when calculating overtime pay. This is especially relevant for employees who regularly receive performance bonuses each month.
It is recommended that companies assess 'wage recognition risks' with human resources or legal consultants when designing policies, and ensure precise written records in labor contracts clearly stipulating the nature of bonuses to minimize dispute risks.
Are Performance Bonuses Taxed? How is Second Generation Health Insurance Calculated?
Income Tax: Salary Income, Separate Deduction for Non-Regular Payments
Performance bonuses are classified as salary income, and if they are not paid on a regular monthly basis, they should have 5% withholding income tax deducted based on the various income withholding rate standards on the payment amount, separate from the total monthly salary. If the payment amount does not exceed the threshold set by the Ministry of Finance for the current year, no withholding is required (but it still needs to be declared); if it exceeds the threshold, 5% will be withheld as a prepayment, with adjustments made when filing the annual tax return in May.
Second Generation Health Insurance Supplementary Premium (Rate: 2.11%)
The supplementary premium is assessed on a cumulative annual basis, with bonuses being the only item among six types of income assessed cumulatively:
- Threshold: Only the part of cumulative bonuses exceeding '4 times the insured salary for that month' is assessed
- Formula: (Annual cumulative bonuses - Insured Salary × 4) × 2.11%
For example, if an employee's insured salary is NT$45,800 and the cumulative bonuses for the year total NT$260,000:
- 4 times threshold: 45,800 × 4 = NT$183,200
- Excess portion: 260,000 − 183,200 = NT$76,800
- Should pay supplementary premium: 76,800 × 2.11% ≈ NT$1,621 (withheld by the employer)
If the total annual bonuses do not exceed the four times threshold, no Second Generation Health Insurance supplementary premium is required.
Practical Advice
Before issuing bonuses, it is recommended that HR check whether the total cumulative bonuses for that employee for the year are about to exceed the four times threshold; if so, supplementary premiums should be withheld at the time of payment, and payments should be made to the Health Insurance Bureau before the end of the next month. If the payroll calculation system is used, it can automatically track annual cumulative amounts and prompt the withholding amounts, reducing manual calculation errors.
How to Use 管理王: Digital Management of Performance Bonuses
The pain points of manually managing performance bonuses are clear: numerous versions of Excel spreadsheets, errors in KPI achievement calculations, payment records scattered across emails and messaging apps, and approval processes relying on paper or Line messages—leading to consolidation only before payroll, making accountability difficult if errors occur.
The 管理王 AI.com.tw Performance Management System integrates KPI setting, monthly assessments, 360-degree mutual evaluations, payroll calculations, making the distribution of performance bonuses systematic from evaluation to account entry:
Step One: Set KPIs and Scoring Criteria in the System
At the beginning of each quarter, supervisors set five to eight KPI indicators for employees in the system while defining bonus multipliers and achievement thresholds for each rating. This way, employees are clear about the rules from day one, avoiding the expectation gap of discovering 'what the boss really wanted was not this' at year-end.
Step Two: Automatic Accumulation Records in Monthly Reviews
At the end of each month, supervisors enter comments and progress in the system, and employees can respond in real-time, with all historical records saved in the cloud, relying not on memory and being secure from turnover-related data loss, providing complete data for annual assessments.
Step Three: AI Automatically Compiles at End of Assessment Period
AI synthesizes performance summaries from KPI achievement rates, 360-degree reviews, and monthly review data, saving supervisors a substantial amount of time on organization so they can focus on evaluating bonus distribution.
Step Four: Linked to Payroll Calculation System for Automatic Calculations
Once performance ratings are confirmed, the system automatically inputs performance bonus amounts based on pre-set formulas, calculating along with overtime pay, labor insurance, health insurance, and second-generation health insurance supplementary premiums, with calculative results traceable to each formula to meet tax audit requirements.
Step Five: Approval Center with Multi-Level Approval
Before distributing bonuses, it goes through an electronic signature approval process, ensuring every payment has written authorization from supervisors and HR, with complete and retrievable approval records, effectively preventing post-issue disputes.
Free plans provide permanent access to basic performance management features, while full AI analysis and multi-level signature functions are available in paid plans. Please refer to the pricing plans or consult the complete performance management guide for more details. For information on KPI versus OKR design, refer to this article What is the Difference Between KPI and OKR?.
Free Consultation on Performance Bonus System Design
Consultants assist you in clarifying labor law regulations and designing legally compliant and transparent performance bonus clauses, addressing all your questions in 30 minutes.
Free consultation hotline: 0800-003-191
LINE Official Account: @119m
Official Website: app.AI.com.tw
Free Trial: Apply for 管理王 now
Frequently Asked Questions
Are Performance Bonuses Mandatory? Is There a Legal Obligation?
Labor regulations do not require employers to distribute 'performance bonuses,' but if the conditions for distribution are stipulated in labor contracts or work rules, the employer is obligated to pay as per the agreement when employees meet those criteria. If an employer arbitrarily withholds, the employee can lodge a complaint with the labor bureau, claiming breach of contract by the employer. Conversely, if the work rules clearly state that 'bonuses are subject to company profits and management approval, not part of guaranteed salary,' the employer may have legal grounds to withhold in loss years. It is recommended to consult with advisors to confirm the wording of clauses before designing systems.
Is Performance Bonus Part of the Basis for Overtime Pay Calculations?
If performance bonuses are classified as wages (having compensation for services and regularly paid), they need to be included in the calculation of overtime pay. The basis for overtime pay calculations is 'normal wages,' and if performance bonuses are recognized as wages, the overtime pay will consequently increase. This is especially crucial for companies that regularly pay performance bonuses each month, as they risk underreporting overtime pay and facing penalties from the labor bureau.
Can Performance Bonuses and Year-End Bonuses Be Designed Together?
Yes, many companies design both types of bonuses: 'Year-End Bonuses' are given after annual settlements based on seniority and job level (more discretionary and non-guaranteed), while 'Performance Bonuses' are distributed based on quarterly or annual KPI ratings (more wage-like). The legal natures of the two differ, as do the applicable labor law recognition standards; thus, it is advisable to define each distinctly in the work regulations and clearly outline their respective calculation methods and distribution conditions.
If an Employee Resigns During the Evaluation Period, Should Their Performance Bonus Be Calculated for That Period?
If performance bonuses are classified as wages, employees who resign during the evaluation period generally have the right to request payment of the performance bonus calculated pro-rata based on their time worked. However, if the work rules state that 'employees who resign are not entitled to that period's bonuses,' the legal enforceability of such a clause is disputed; it is recommended to negotiate with employees or consult legal advisors when designing systems to reduce potential disputes.
Is the Tax Treatment of Performance Bonuses for Foreign Employees the Same as for Taiwanese Employees?
The tax treatment of foreign employees differs based on their duration of stay in Taiwan. Foreign employees who reside in Taiwan for 183 days or more are subject to the same income tax reporting as local employees; those who stay for less than 183 days generally handle their wage income (including performance bonuses) at a higher withholding rate. It is advisable to consult the National Taxation Bureau or a tax advisor in advance to avoid incorrect withholdings.
Sources
- Ministry of Labor Labor Law Query System: Performance Bonus Explanation Letter No. 035198
- National Regulatory Database: Labor Standards Act, Articles 2, 29
- National Regulatory Database: Labor Standards Act Implementation Rules, Article 10
- Ministry of Labor Official Website: New Severance Pay Calculation Explanation
- Ministry of Finance Tax Portal: Standards for Withholding Income Tax
- Ministry of Health and Welfare Central Health Insurance Bureau: Explanation of Second Generation Health Insurance Supplementary Premiums
This article is for general informational purposes and does not constitute legal or tax advice. Actual regulations are subject to the latest announcements from relevant authorities.